Why Finance an E-Rickshaw?
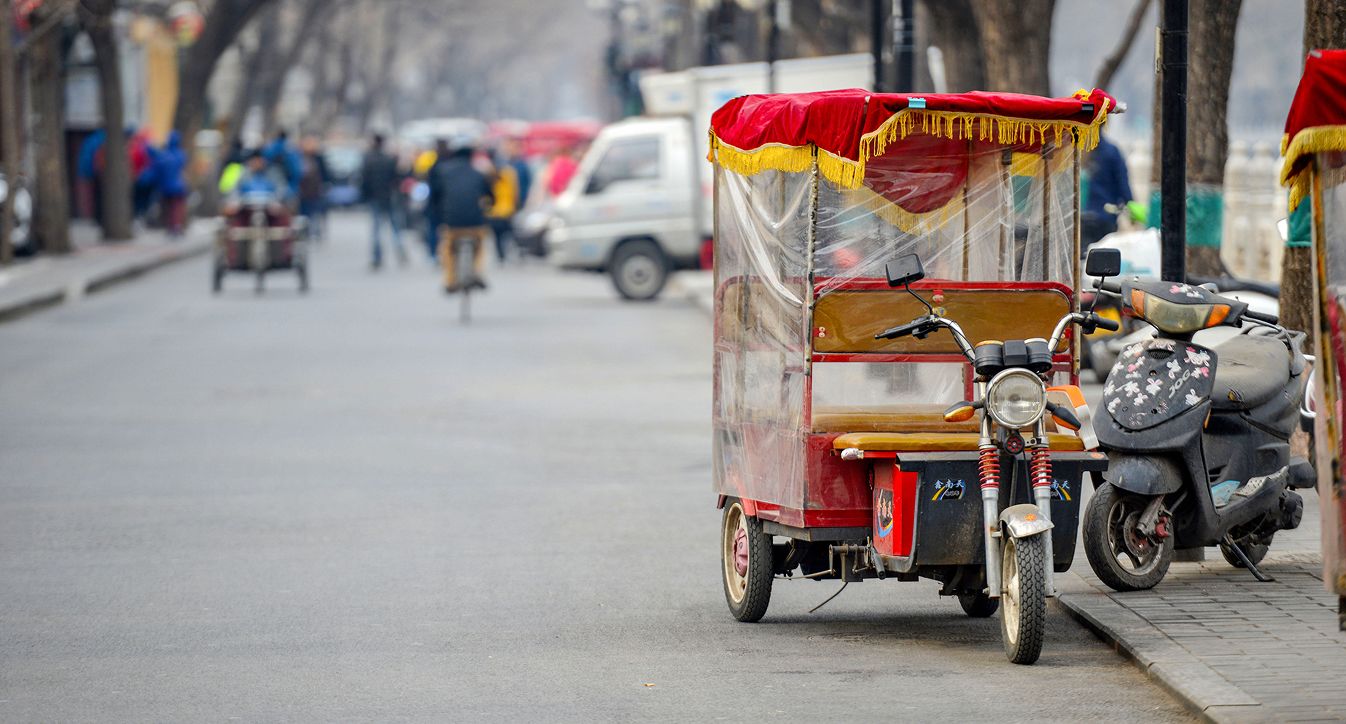
Buying an e-rickshaw often requires a big upfront investment. Depending on the model and battery type, it can cost anywhere between INR 1.2 to INR 2.5 lakh or even more. For many first-time buyers—especially those without savings or new to credit, taking a loan is often the only practical option. Financing helps you:What Makes an E-Rickshaw Finance Company Safe?
Many companies offer e-rickshaw loans, but not all of them are dependable. Some come with unclear terms, hidden fees, or poor customer service—often leaving borrowers stuck or confused. A safe finance company is transparent, digitally enabled, regulated, and supportive throughout the loan journey. Here’s what to check:1. Is the Company Regulated?
Always start by checking if the lender is a registered Non-Banking Financial Company (NBFC) and regulated by the Reserve Bank of India (RBI). This means they follow strict rules on interest rates, disclosures, and customer protection. Revfin Capital (Aristo Securities), which is a subsidiary of Revfin, for example, is an RBI-registered NBFC and is fully compliant with RBI regulations. That means ethical lending practices, clear terms, and no surprises.2. Do They Offer Transparent Loan Terms?
A good finance company makes everything clear upfront. Interest rates, EMI schedules, and penalties—these should all be shared in writing. You should receive a copy of your loan agreement with no hidden charges or confusing fine print. Revfin ensures full transparency. Borrowers know their terms from day one, and all documents are available digitally for easy access.3. How Do They Treat New-to-Credit Borrowers?
Many people applying for e-rickshaw loans have never taken a loan before. Traditional banks might reject them due to a lack of credit history. But a supportive lender will find alternative ways to understand whether you can repay the loan. Revfin uses digital tools like psychometric testing to evaluate your repayment intent, not just your past credit record. That means even first-time borrowers have a fair chance at ownership.4. What is the Loan Approval Process Like?
A secure loan process doesn’t involve middlemen, cash dealings, or long waits. You should be able to apply directly—via a mobile app or through authorized dealers—without paying anything upfront. Revfin offers a completely online journey. From application to disbursal, everything is digital. Most approvals happen within hours, and in many cases, vehicles are delivered the same day. You stay in control throughout.5. Do They Support You After the Loan Is Approved?
Many people overlook the importance of post-loan support. What if your vehicle gets stolen? What if there’s a dispute about your EMIs? Do you have access to help? Reliable lenders don’t disappear after giving you the loan. They protect your vehicle using technologies like GPS tracking, geofencing, and remote-control locking. Revfin, for instance, uses RevIoT, smart telematics to ensure your e-rickshaw stays safe and with the rightful owner.How Revfin Ensures Safety for E-Rickshaw Borrowers
Revfin has taken every step to make e-rickshaw loans not just accessible but also secure and stress-free for individuals looking to use the vehicle for daily income.- RBI-Regulated NBFC:
- Online Application:
- Quick Disbursal:
- Inclusive Lending:
- Post-Sale Security:
- Support for Refurbished EVs:
What Should You Avoid?
Not every financier plays by the rules. Watch out for these red flags:Final Thoughts
Taking a loan for an e-rickshaw is a major step toward financial independence. But the lender you choose matters just as much as the vehicle you buy. A safe and reliable finance partner helps you start earning without stress or risk. Revfin has built its reputation on trust, technology, and transparency. With its digital-first process and commitment to empowering everyday earners, Revfin makes e-rickshaw ownership simple, secure, and sustainable. If you’re ready to buy an e-rickshaw and want to finance it safely, Revfin can guide you every step of the way.